Corporate Advisory Takeaways at a Glance
- Capital Expenditure Incentive: 200% capital allowance available for qualifying investments in export manufacturing and tourism.
- Tax Rate Stability: Baseline standard corporate income tax preserved at 30% without retrospective levies.
- Execution Imperative: Prompt publication of Inland Revenue circulars required to unlock private investment decisions.
- Revenue Administration: Full deployment of RAMS and automated audit systems demanded to ensure fair compliance.
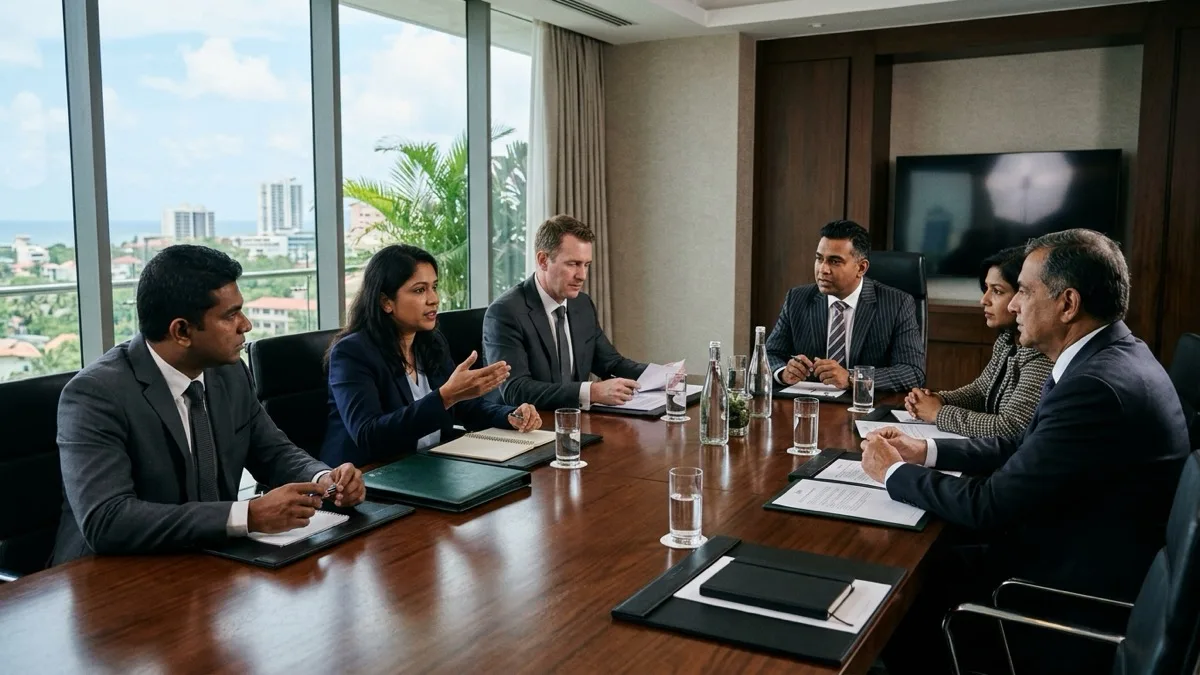
COLOMBO (SriLankaBiz): Formulating a resilient post-budget corporate strategy requires immediate operational clarity on capital allowance deductions and statutory tax administration, senior partners at Ernst & Young and Deloitte Sri Lanka urged during post-budget executive symposiums in Colombo.
Addressing chief financial officers, corporate directors, and tax leaders following the presentation of Budget 2027, advisory specialists noted that Sri Lanka has successfully transitioned from emergency economic stabilization toward investment-led structural growth. However, realizing the administration’s projected 6.0% medium-term economic expansion depends entirely on how swiftly fiscal authorities translate budgetary proposals into gazetted tax statutes.
Why Post-Budget Corporate Strategy Focuses on Capital Deductions
The centerpiece of Budget 2027 for private enterprise is the reintroduction of targeted capital allowances. Under the proposed framework, qualifying businesses investing in export-oriented manufacturing, value-added agriculture, and tourism infrastructure can deduct 200% of their qualifying capital expenditure from assessable income over specified horizons.
Tax directors emphasize that every post-budget corporate strategy must evaluate whether planned automation, factory expansion, and green technology adoption qualify under these enhanced provisions. By substituting passive tax holidays with investment-linked deductions, the government rewards balance sheet reinvestment while ensuring base revenue contributions to public coffers.
| Fiscal Area | Budget 2027 Policy Direction | Advisory Recommendation | Corporate Action |
|---|---|---|---|
| Corporate Income Tax | Maintained at standard 30% baseline rate | Avoid ad-hoc sector super-taxes or levies | Model three-year operating cash flows |
| Capital Allowances | 200% CapEx deduction for exports and tourism | Issue clear eligibility circulars immediately | Accelerate qualifying capital equipment tenders |
| Indirect Tax Compliance | Digital invoice matching through RAMS | Enhance audit transparency and refund timelines | Upgrade ERP systems for automated e-filing |
| Public Capital Spending | Rs. 2 Trillion allocated for infrastructure | Prioritize public-private partnerships | Target logistics and regional subcontracting |
Digitalization and Resolving Tax Administration Friction
Tax specialists at Deloitte highlighted that policy intent often falters during administrative implementation. While central government revenue exceeded 16% of GDP in 2026, corporate taxpayers frequently encounter delays in Value Added Tax (VAT) refund processing and dispute resolution at the Inland Revenue Department.
A successful post-budget corporate strategy must integrate advanced tax technology to manage real-time reporting under the Revenue Administration Management System (RAMS). Panelists urged the Ministry of Finance to establish binding service-level agreements for statutory refunds, preventing working capital bottlenecks across export manufacturing supply chains.
Strategic Roadmap for Corporate Leadership
Senior advisory partners concluded that building a competitive post-budget corporate strategy requires proactive engagement with regulatory bodies. With headline inflation projected to test 9.0% and the Central Bank tightening benchmark interest rates, corporate balance sheets will face elevated financing expenses over the coming quarters.
By leveraging capital allowances, automating tax compliance, and optimizing supply chain logistics, Sri Lankan corporate leaders can preserve operating margins while expanding export market footprints. Advisory leaders stressed that predictable economic governance remains the essential catalyst to convert legislative budget targets into durable enterprise investments.