Shorter-dated bills drew acceptances above the amount offered, while the 12-month tenor fell short, as weighted average yields rose by 2 to 5 basis points.
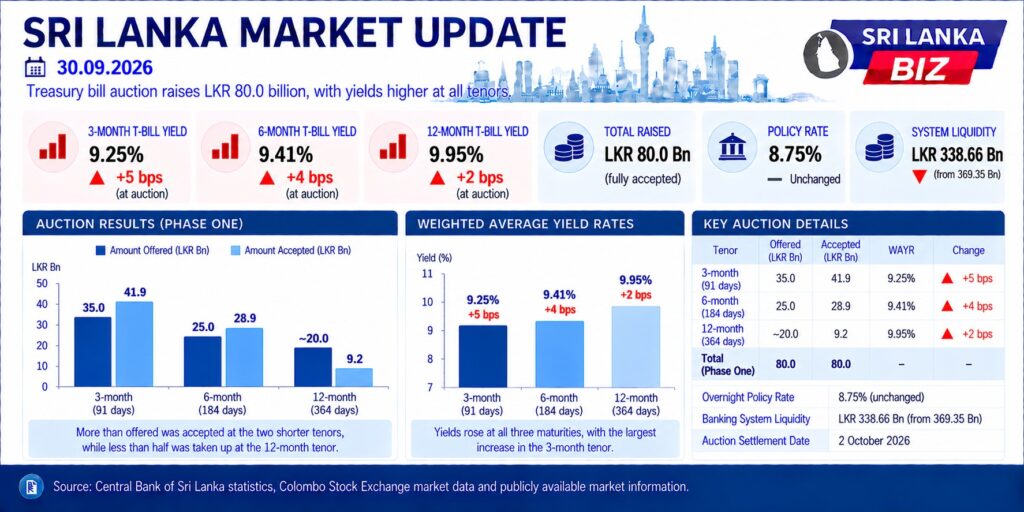
Sri Lanka’s Public Debt Management Office (PDMO) raised LKR 80.0 billion at its weekly Treasury bill auction, matching the total amount offered. Weighted average yield rates (WAYR) rose at all three maturities.
The result covers the first phase of the auction only. Phase two results will be published after the second phase concludes.
Yields rise at every tenor
- 3-month bills: 9.25%, up 5 basis points
- 6-month bills: 9.41%, up 4 basis points
- 12-month bills: 9.95%, up 2 basis points
The increases were small, and the pattern was uneven. The largest rise came in the shortest tenor, and the smallest in the longest.
Where the money was raised
The PDMO accepted more than it offered in the two shorter tenors. For 3-month bills it accepted LKR 41.9 billion against LKR 35.0 billion offered, and for 6-month bills LKR 28.9 billion against LKR 25.0 billion offered.
For 12-month bills, it accepted only LKR 9.2 billion, below the amount offered. Because the total accepted matched the total offered, the offer for this tenor works out to about LKR 20 billion, which means less than half was taken up. In effect, the PDMO shifted borrowing toward shorter maturities.
How the auction fits the wider market
The auction was held on the same day the Central Bank of Sri Lanka (CBSL) kept the Overnight Policy Rate at 8.75%. The 3-month yield now sits 50 basis points above the policy rate.
Liquidity in the banking system contracted to LKR 338.66 billion from LKR 369.35 billion the previous day. Settlement of the auction is scheduled for 2 October, and the settlement may draw further on that liquidity. The data do not show whether the two are linked.
Business Impact
T-bill yields are the reference point for the cost of short-term funding in the economy. Banks use them to price short-term loans and deposits, and corporate treasurers use them to benchmark returns on idle cash.
Slightly higher yields at auction suggest short-term funding costs are not easing. The reduced uptake at the 12-month tenor also shows that the government is leaning on shorter-dated borrowing at this auction. For businesses with short-term credit lines or working capital facilities, rates remain near current levels, and the policy rate hold means no direct upward pressure from the central bank.
Key Numbers
| Tenor | Offered (LKR Bn) | Accepted (LKR Bn) | WAYR | Change |
|---|---|---|---|---|
| 3-month (91 days) | 35.0 | 41.9 | 9.25% | +5 bps |
| 6-month (184 days) | 25.0 | 28.9 | 9.41% | +4 bps |
| 12-month (364 days) | about 20.0* | 9.2 | 9.95% | +2 bps |
| Total (phase one) | 80.0 | 80.0 | n/a | n/a |
*Derived from the total offered and the other two tenors.
| Other indicators | Level |
|---|---|
| Overnight Policy Rate | 8.75% (unchanged) |
| Banking system liquidity | LKR 338.66 Bn (from LKR 369.35 Bn) |
| Auction settlement date | 2 October |
Source Attribution
Source: Central Bank of Sri Lanka statistics, Colombo Stock Exchange market data and publicly available market information.