Buying interest concentrated in shorter maturities pushes yields down up to 2033, while 2034 and 2035 bonds edge higher
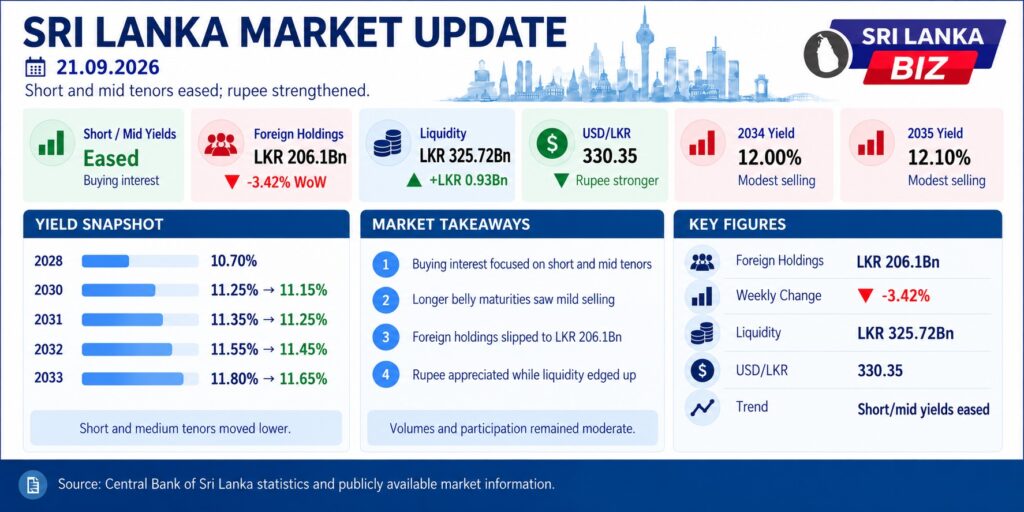
Yields on short- and medium-term government securities eased in the latest session as buying interest concentrated in these tenors, while longer-dated bonds at the belly of the curve saw modest selling pressure, according to secondary market activity.
The downward adjustment in yields extended from the shorter end of the curve up to bonds maturing in 2033, reflecting sustained demand for these tenors. At the short end, the 15.12.2028 maturity traded at 10.70%, while the 01.08.2030 and 15.10.2030 maturities both changed hands in a range from 11.25% down to 11.15%.
Further along the curve, the 01.02.2031 bond traded between 11.35% and 11.25%, while the 01.10.2032 and 15.12.2032 maturities both traded within a 11.55%–11.45% range. At the belly of the curve, the 15.01.2033 and 01.11.2033 bonds traded between 11.80% and 11.65%.
In contrast, longer-dated maturities at the belly end of the curve saw modest selling interest. The 15.06.2034 bond traded at 12.00%, while the 15.06.2035 maturity traded higher, at 12.10%. Despite the selling interest in this segment, yields there remained largely stable overall.
Both investor participation and traded volumes were described as moderate through the session. Separately, foreign holdings of government securities declined 3.42% week-on-week, falling to LKR 206.1 billion from LKR 213.4 billion the previous week, extending a pullback after holdings had risen steadily over the preceding several weeks.
Banking system liquidity edged up marginally to LKR 325.72 billion, compared to LKR 324.79 billion previously, while the rupee strengthened against the US dollar to LKR 330.35, from LKR 332.13 in the prior session.
Key Numbers
| Tenor / Maturity | Yield / Range | Movement |
|---|---|---|
| 15.12.2028 | 10.70% | Traded |
| 01.08.2030 / 15.10.2030 | 11.25% → 11.15% | Down |
| 01.02.2031 | 11.35% → 11.25% | Down |
| 01.10.2032 / 15.12.2032 | 11.55%–11.45% | Down |
| 15.01.2033 / 01.11.2033 | 11.80% → 11.65% | Down |
| 15.06.2034 | 12.00% | Modest selling |
| 15.06.2035 | 12.10% | Modest selling |
| Foreign Holdings of G-Secs | LKR 206.1 Bn | -3.42% WoW |
| Banking System Liquidity | LKR 325.72 Bn | +LKR 0.93 Bn |
| USD/LKR | 330.35 | Rupee appreciated |
Business Impact
The easing of short- and medium-term yields signals continued investor appetite for government securities in these tenors, which could translate into marginally lower borrowing costs for instruments benchmarked against these maturities. The selective softness at the longer end of the curve, however, suggests investors remain more cautious about locking in returns beyond 2033, a factor corporate treasurers and institutional investors managing long-duration portfolios should factor into their positioning. The weekly decline in foreign holdings of government securities is worth monitoring going forward, as sustained foreign selling in this segment could put upward pressure on yields if the trend continues. Businesses and financial institutions with exposure to the local bond market should track this weekly foreign holdings trend alongside daily yield movements for a fuller picture.
Source Attribution
Source: Central Bank of Sri Lanka statistics and publicly available market information.