Equities closed higher for a second session as trading activity stayed below the monthly average, while government securities yields adjusted lower from the belly to the long end of the curve.
Key Highlights
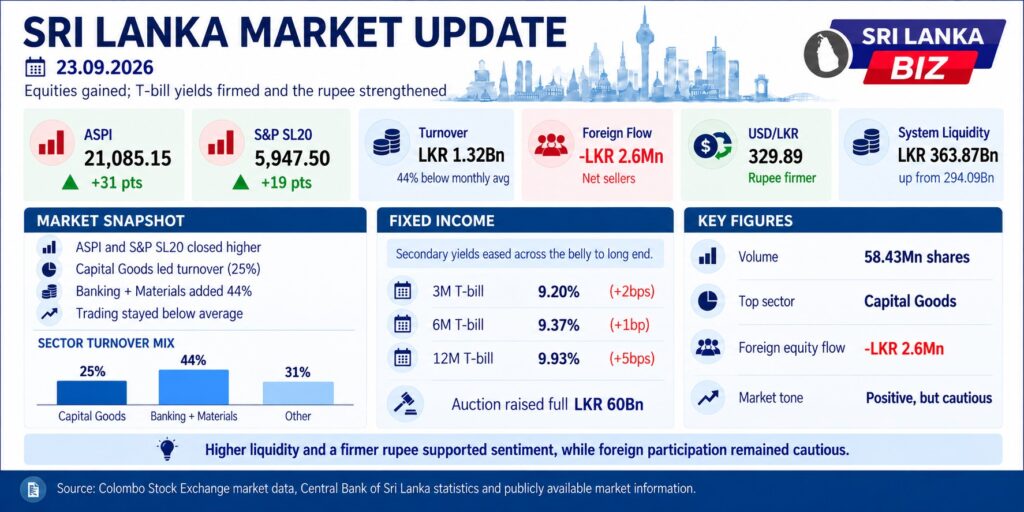
The Colombo Stock Exchange closed higher on Wednesday, with both benchmark indices extending recent gains. Trading activity remained subdued compared to the monthly average, and foreign investors were marginal net sellers for the session. In fixed income markets, secondary market yields moved lower along the belly-to-long end of the curve on a weekly basis, while the central bank’s primary market T-Bill auction saw yields rise across all three tenors offered.
Stock Market Summary
The All Share Price Index (ASPI) added 31 points to close at 21,085.15, while the S&P SL20 index gained 19 points to end at 5,947.50. Daily turnover totalled LKR 1.32 billion, a decline of roughly 44% from the monthly average of LKR 2.3 billion. The Capital Goods sector accounted for the largest share of turnover at 25%, with the Banking and Materials sectors together contributing a further 44%. Foreign participation recorded a net outflow of LKR 2.6 million for the day.
Fixed Income Summary
Secondary market government securities yields eased from the belly to the long end of the curve compared with the prior session, with trading activity described as moderate. The Public Debt Management Office concluded its weekly Treasury Bill auction, raising the full LKR 60 billion offered. Weighted average yield rates rose by 2 basis points to 9.20% for the 3-month bill, by 1 basis point to 9.37% for the 6-month bill, and by 5 basis points to 9.93% for the 12-month bill.
Currency Market Update
The rupee appreciated against the US dollar, trading at LKR 329.89 compared with LKR 330.81 in the previous session. Liquidity in the domestic banking system expanded to LKR 363.87 billion, up from LKR 294.09 billion previously.
Business Impact
Stable-to-firming short-term yields and expanded system liquidity are relevant reference points for businesses managing short-term borrowing and treasury operations. The modest rupee appreciation offers marginal relief for importers, while exporters may see a slightly reduced currency tailwind. Continued foreign selling on the equity market, evident in year-to-date outflows, remains a factor for companies reliant on foreign portfolio participation.
What to Watch Next
Market participants will watch for the release of Phase Two T-Bill auction results, further movement in system liquidity, and whether foreign equity flows stabilise following the recent multi-month outflow trend.
Key Numbers
| Metric | Value |
|---|---|
| ASPI | 21,085.15 (+31 pts) |
| S&P SL20 | 5,947.50 (+19 pts) |
| Daily Turnover | LKR 1.32 Bn |
| Foreign Flow (Daily) | -LKR 2.6 Mn |
| 3M T-Bill WAYR | 9.20% (+2 bps) |
| 6M T-Bill WAYR | 9.37% (+1 bp) |
| 12M T-Bill WAYR | 9.93% (+5 bps) |
| USD/LKR | 329.89 |
| System Liquidity | LKR 363.87 Bn |
Source: Colombo Stock Exchange market data, Central Bank of Sri Lanka statistics and publicly available market information.