Secondary market buying emerges across most maturities even as same-day T-bill auction yields moved higher and foreign holdings declined
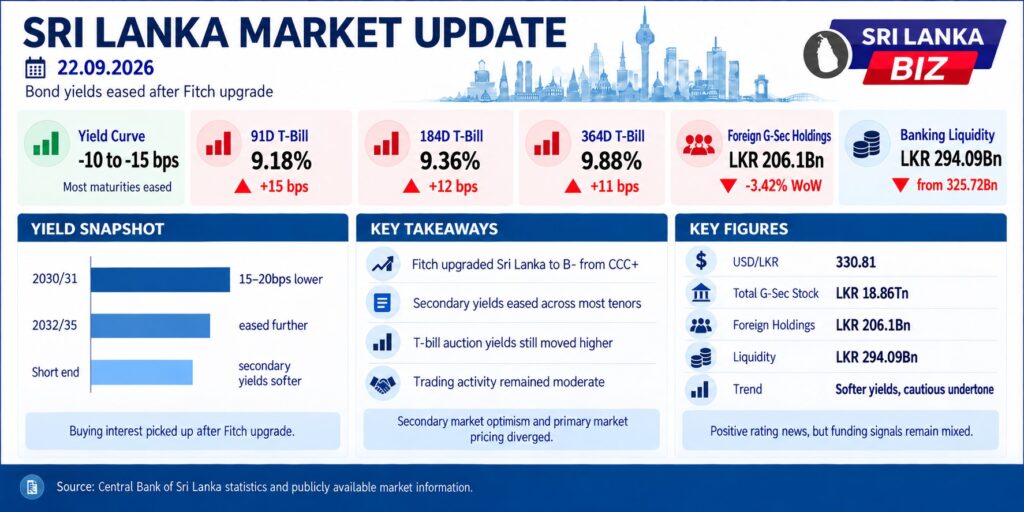
Sri Lanka’s secondary market yield curve for government securities eased by 10 to 15 basis points across most maturities, as buying interest picked up following Fitch Ratings’ upgrade of the country’s sovereign credit rating to B- from CCC+.
The session began on a weaker footing, with yields under mild selling pressure ahead of the rating announcement. Sentiment shifted once the upgrade was confirmed, with buying momentum emerging across the curve through the remainder of the day. Trading activity and investor participation were described as moderate rather than heavy.
Movement was broad-based across tenors. Bonds maturing in 2030 and 2031 traded within ranges roughly 15-20bps tighter than prior levels, while longer maturities in the 2032 to 2035 range saw yields compress by a similar magnitude, with some tenors edging down as much as 35bps compared to the prior week.
Not every part of the fixed income market moved in the same direction. A same-day Treasury bill auction told a different story: yields on the 91-day, 184-day and 364-day bills all rose, by 15, 12 and 11 basis points respectively, compared to the previous auction. The divergence suggests that while secondary market sentiment turned more favorable on the rating news, primary market pricing had not yet fully reflected the same optimism at the time of the auction.
Foreign holdings of local government securities also moved against the day’s positive narrative, falling 3.42% week-on-week to LKR 206.1 billion, down from LKR 213.4 billion the prior week. Market liquidity in the banking system contracted to LKR 294.09 billion, compared to LKR 325.72 billion previously, while the LKR depreciated modestly against the US dollar to 330.81, from 330.35.
Key Numbers
| Metric | Value |
|---|---|
| Secondary market yield movement | -10 to -15bps across most of the curve |
| 91-day T-bill yield (auction) | 9.18% (+15bps) |
| 184-day T-bill yield (auction) | 9.36% (+12bps) |
| 364-day T-bill yield (auction) | 9.88% (+11bps) |
| Foreign holdings of G-secs | LKR 206.1Bn (-3.42% WoW) |
| Banking system liquidity | LKR 294.09Bn (from LKR 325.72Bn) |
| USD/LKR | 330.81 (from 330.35) |
| Total outstanding G-sec stock | LKR 18,856,403Mn (+0.76% WoW) |
Business Impact
A softer secondary market yield curve is generally a positive signal for the cost of government borrowing over time and can filter through to corporate lending rates as banks reprice against government securities benchmarks. However, the rise in primary market T-bill yields and the pullback in foreign holdings of government debt point to a more cautious undertone beneath the headline move, one that businesses and treasury managers tracking funding costs should weigh alongside the positive rating news rather than in isolation.
Source Attribution
Source: Central Bank of Sri Lanka statistics and publicly available market information.